Mortgage in Spain – Find Out What Property You Can Afford
Do You Really Need to Have the Full Amount to Buy Property in Spain?
No. And that is exactly why it is worth checking how much financing a property purchase in Spain could actually cost you — especially if you want to keep part of your capital available for investments, your business or simply as a financial safety net.
The Spanish mortgage market is open to foreign buyers and non-residents. You therefore do not need to live in Spain, work in Spain or receive a salary from a Spanish employer to apply for a mortgage with a Spanish bank.
And this is something worth knowing before assuming:
“Spain? I probably have to pay everything in cash or take out a mortgage in my own country.”
Would you like to check the financing options available for your property in Spain?
Find out how we can help you obtain a mortgage ↘
First, let’s look at the numbers
Imagine that you need a €300,000 mortgage over 20 years.
We are not comparing the property price here. €300,000 is the financing amount, which allows us to see how differences in interest rates translate into real money.
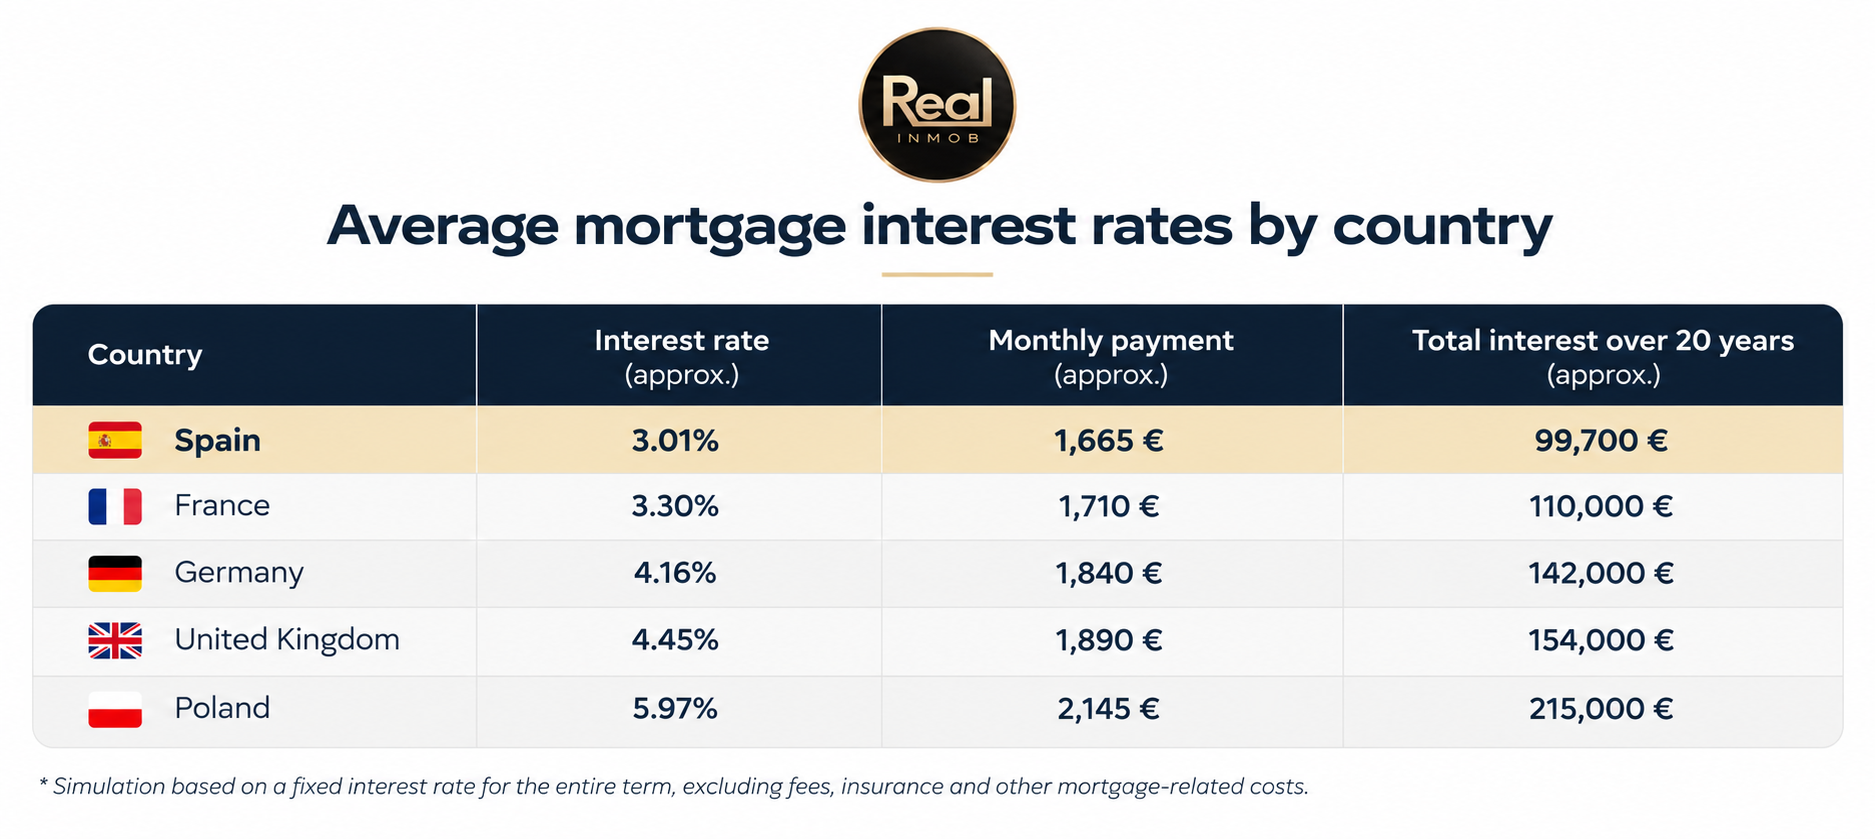
Indicative mortgage interest rates in the different countries give us the following picture:
🇪🇸 Spain
Interest rate: 3.01% per year
With a standard equal-payment repayment system, the monthly payment would be approximately €1,665.
Interest over 20 years: approx. €99,700
🇫🇷 France
Interest rate: approx. 3.30%
Monthly payment: approx. €1,710 / month
Interest over 20 years: approx. €110,000
🇩🇪 Germany
Interest rate: approx. 4.16%
Monthly payment: approx. €1,840 / month
Interest over 20 years: approx. €142,000
🇬🇧 United Kingdom
Interest rate: approx. 4.45%
Monthly payment: approx. €1,890 / month
Interest over 20 years: approx. €154,000
🇵🇱 Poland
Interest rate: approx. 5.97%
Monthly payment: approx. €2,145 / month
Interest over 20 years: approx. €215,000
* Simulation assuming a fixed interest rate throughout the entire period, excluding commissions, insurance and other mortgage-related costs.
Source for the Spain example: own calculation based on an annual interest rate of 3.01% and a 20-year mortgage term, using a standard equal-payment repayment system.
As you can see, the difference is far from insignificant.
With the same €300,000 mortgage and a 20-year term, the difference between the example financing in Spain and Poland would be approximately:
€480 less per month
and approximately
€115,000 less in interest over the full term.
This difference can matter for the investment as a whole
With a €300,000 mortgage, we are not talking about a difference of a few euros a month. The difference in interest rates can translate into tens of thousands of euros over the entire financing period.
That is why, if you are planning to buy property in Spain, it is worth looking not only at the property price, but also at where and on what terms you will finance the purchase.
And this is precisely why a Spanish mortgage can also be an interesting option for someone who lives and earns their income in another European country.
Of course, actual bank offers depend on the client's profile, down payment, type of interest rate, income and other parameters. These figures should therefore be treated as a reference point, but they illustrate the difference in financing costs between the different countries.
Importantly, a mortgage can finance the purchase of both new-build and resale property.
Can I Get a Mortgage in Spain as a Foreigner?
Yes. Spanish banks offer specific solutions for foreign buyers and non-residents from different parts of the world. These options are available not only to clients from various European countries, but also to buyers from other international markets, including the United States, Canada and the United Arab Emirates, including Dubai.
For example, CaixaBank, as part of its offering for foreign buyers, processes mortgage applications for clients living in various countries and states that financing of up to 70% of the property's value may be available, depending on the client's profile and the financing terms.
This means that you do not need a Spanish salary to obtain a Spanish mortgage.
The bank can assess income earned in your country of residence, its stability, your existing financial commitments, credit history and other aspects of your financial situation.
Do you earn your income outside Spain? That does not necessarily have to be an obstacle to obtaining financing.
Ask about your financing options ↘
70% Financing — What Does It Mean in Practice?
Let’s assume a property worth:
€430,000
With 70% financing:
€300,000 — mortgage
€130,000 — your own capital
Taxes and purchase-related costs would then be added to this amount.
In other words, you do not need to provide the full €430,000 from your own pocket.
Under CaixaBank's offer for foreign buyers, the bank indicates financing of up to 70%, while the buyer provides the remaining 30% of the purchase price, together with the funds needed for taxes and other transaction costs. Depending on the situation, this means approximately 42–45% of the property's value in own funds when these additional costs are also taken into account.
If the property costs €430,000, this does not mean that you need to have the entire amount available in your bank account.
With 70% financing, we are talking about approximately €300,000 in mortgage financing and €130,000 in your own funds, plus the purchase costs.
That is why it is worth asking:
“How much of my own capital do I need and how much can I borrow?”
This calculation helps determine whether a particular property really fits within your budget.
Who Buys Property in Spain with a Mortgage?
Spain has been attracting buyers from across Europe for years, and foreign buyers represent an important part of the property market.
Interestingly, according to CaixaBank Research data for the first half of 2025, German buyers accounted for 17.1% of mortgage applications submitted by non-residents. British buyers, meanwhile, led in terms of the number of property purchases made by foreign buyers.
This shows the scale of the phenomenon.
A Spanish mortgage for foreigners is therefore not a niche solution designed for one particular nationality.
It is a normal part of the Spanish property market.
The Bank Looks at More Than Just Your Salary
When assessing a mortgage application, there is much more to consider than the level of income alone.
The bank may assess, among other things:
employment or business stability,
the amount and source of income,
existing financial commitments,
credit history,
the borrower's age,
country of tax residence,
the currency in which you earn your income,
the amount of your own funds,
the value and type of property.
That is why two people earning exactly the same amount can receive completely different mortgage decisions.
Your entire financial profile matters.
A Mortgage Does Not Have to Mean “Living on Credit”
Why take out a mortgage if you can buy a property with cash?
Because this is not about whether you can pay the full amount. It is about whether you want to tie up all your capital in a single property.
If you have €430,000 and can buy a property in cash, you could also consider using part of that capital as a down payment and financing the remainder with a mortgage.
The remaining funds could be kept as:
investment capital,
a financial reserve,
funds for developing your business,
or simply additional financial security.
A mortgage can therefore be more than just a way to buy a property you “cannot afford”.
It can also be a tool for managing your own capital.
Would you like to find out how to finance a property purchase in Spain while keeping part of your own capital available?
Contact us ↘
Before You Buy — Check the Financing
You do not have to choose a property first and only then wonder whether you can afford it.
At Real Inmob, we help you assess your financing options and match the purchase to your budget, and then guide you through the entire process — from choosing the property, through the mortgage and formalities, to completing the transaction.
Find out what property in Spain you can realistically afford.
Discover the full scope of our 360° service ↘
Would you like to check the financing options available for your property in Spain?
Images
Share


 Back